Smart shopping carts: retailers face a difficult choice after Instacart exit

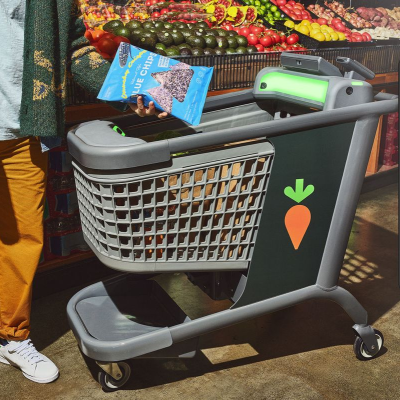
Instacart’s decision to discontinue its Caper smart carts leaves supermarket groups facing a rethink. Carrefour Belgium’s trial is now on hold, while Morrisons is ending its smart cart pilot. Other retailers using Caper, including US Kroger, Wakefern, Schnucks and Australian Coles, will need clarity on future servicing and support as the business winds down by Q2 2027.

The withdrawal does not mean the technology failed with shoppers. Instacart reported Net Promoter Scores above 70 at established locations and claimed double-digit basket growth across retail partners. An on-screen “Got everything?” prompt reportedly lifted basket size by almost one percentage point. Separately, a 2026 Bayes Business School study of 12,418 shopping sessions at a German supermarket found smart-cart users spent 32% more and bought 25% more items on average.

The problem was scale, not necessarily shopper appeal. Instacart said retailer adoption had not grown quickly enough to justify continued investment. Smart carts require hardware, maintenance and systems integration; retailers must persuade customers to use them and demonstrate returns across stores.

Alternatives remain. Amazon continues to develop its Dash Cart, while Veeve, Shopic and Israel-based Cust2Mate offer smart-cart or retrofit solutions. Carrefour already works with Cust2Mate in France and Israel, and Belgium’s Colruyt has developed its own Smart Cart. These options differ in functionality and availability, so they are not automatic replacements.

So, the end of Caper does not mean the end of smart shopping carts. Instacart’s withdrawal does, however, highlight the challenges of rolling out new technology across large supermarket networks, where investment, maintenance and customer adoption all need to add up commercially. 
Cyberattacks expose retailers’ vulnerability

Cyberattacks on supermarkets are posing new threats, with recent incidents showing that digital interference can have consequences far beyond websites, payment systems and customer data. 

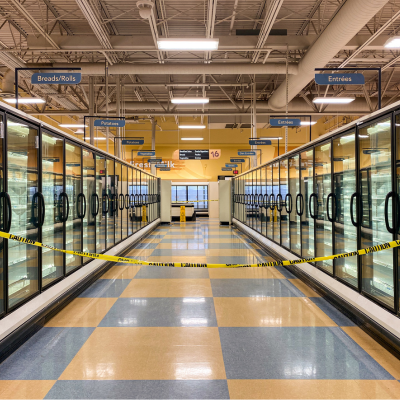
On 2 November, supermarkets in Belgium, Luxembourg, Sweden and Estonia reported overnight refrigeration problems. Delhaize confirmed an IT incident affecting cooling systems in dozens of stores. Colruyt reported five affected shops, while Sweden’s ICA and Coop also experienced incidents. Investigations are ongoing, and there is no confirmation that the attacks are connected.

The incidents follow a major attack in France in October, when hackers manipulated connected refrigeration controllers at hundreds of supermarkets, forcing units into defrost mode. Temperatures reached 50°C, resulting in spoiled stock, fires at some locations and damage estimated in the tens of millions of euros.

The disruption is not limited to refrigeration. In October, a cyber incident at Ahold Delhaize led to precautionary shutdowns affecting websites, apps, online orders and logistics across several European and US banners. The 2025 attacks on M&S and Co-op, alongside the ransomware incident at supply-chain technology provider Blue Yonder, offer further reminders of how quickly disruption can spread between businesses.

Behind these incidents is a growing dependence on connected systems throughout the food chain. Refrigeration, warehouse management, production equipment and building controls are increasingly networked, sometimes with remote access for external contractors. These connections can become entry points when software is outdated, passwords are weak or systems are poorly separated from corporate networks.

The consequences are tangible: lost stock, interrupted deliveries, production delays, food-safety concerns and damaged customer confidence. As more physical operations depend on connected technology, protecting those systems is becoming as important as securing company data. Cyber resilience is becoming part of keeping shelves stocked and supply chains moving, not simply an IT concern.

Eurelec brings European pricing practices to the fore

Ten years after its creation, European buying alliance Eurelec is setting its sights on greater transparency in cross-border pricing. As the partnership between E.Leclerc, Rewe and Ahold Delhaize enters its second decade, understanding the differences in commercial conditions between national markets is becoming a central part of its agenda.

Operating across eight countries, Eurelec recorded purchasing volumes of €13.39bn in 2025, up 8.3%, and expects to approach €15bn in 2026. It now works with 46 major multinational suppliers, giving it a broad view of pricing practices across several European markets.

The alliance argues that purchasing prices for identical products, sometimes manufactured in the same factory, can vary by as much as 40% between countries. While differences in local costs, market conditions and commercial strategies may explain some of this variation, Eurelec believes that greater transparency is needed to understand the reasons behind it.

Territorial supply restrictions are another focus. Country-specific distribution arrangements can limit access to purchasing conditions available in neighbouring markets, raising questions about the practical functioning of the EU Single Market.

The debate also highlights the regulatory complexity of European trade. Eurelec's ongoing disagreement with French authorities over the application of national commercial law to contracts negotiated in Belgium illustrates how national legislation can continue to complicate cross-border business, despite decades of European market integration.

More broadly, the situation underlines a persistent contradiction at the heart of the European grocery market: retailers and suppliers increasingly operate across borders, yet commercial conditions and regulatory frameworks remain largely shaped by individual national markets.

Aldi Belgium steps up app-based promotions, puts private labels in the spotlight

Aldi Belgium is strengthening its digital loyalty strategy by rolling out around ten exclusive promotions each week for app users, placing fresh food and private label products at the heart of the initiative.

The additional offers, which run alongside Aldi’s regular weekly specials, cover categories including fresh fruit and vegetables, meat, fish and the retailer’s own brand range. Discounts are automatically applied at checkout when customers scan their Aldi app, making the savings immediate and requiring no additional steps.

The move builds on Aldi Belgium’s loyalty programme, introduced across its stores last year. Members can collect points to exchange for free products or further discounts. According to Aldi, the programme has gained traction, with increasing numbers of shoppers regularly using the app.

The strategy also reflects changing consumer expectations. Research conducted by iVOX on behalf of Aldi found that three-quarters of Belgian consumers primarily expect immediate discounts at checkout from loyalty programmes. Aldi’s latest initiative directly responds to this demand, while providing an additional incentive for shoppers to engage digitally.

Interestingly, Belgium serves as the exclusive testing ground for Aldi's app-based discounts. This contrasts with Aldi’s approach in almost all other markets, including Germany, the UK and Australia, where the discounter explicitly rejects loyalty schemes and treats them publicly as a marketing enemy.

EU steps up support for domestic protein production

The European Commission is stepping up efforts to increase domestic production of protein crops, aiming to reduce reliance on imports, strengthen supply resilience and support more sustainable farming systems.

Under its new Protein Action Plan, published in July 2026, the Commission aims to raise the share of protein from oilseeds and protein crops used as animal feed that is produced in the EU from 25.8% today to 35% by 2035. The focus is on crops such as pulses and soya that can be grown under European conditions.

The EU remains particularly dependent on imports for high-protein feed. In 2025, only 25% of protein from oilseeds and protein crops used as animal feed was sourced within the EU. Soya accounts for the largest share of these imports: in 2024–25, the EU imported 13.4 million tonnes of soya bean and soya meal protein, mainly from Brazil, Argentina and the United States.

The Commission plans to encourage farmers to grow more protein crops through a combination of Common Agricultural Policy measures, investment in storage and processing, and stronger links between farmers and other parts of the value chain. Research into seeds, crop resilience, processing and resource efficiency will also form part of the strategy.

In addition, the strategy aims to increase the use of protein crops in human food. Greater availability of locally produced pulses and other protein-rich crops could broaden the supply of regional ingredients, while origin labelling, public procurement and EU-funded promotion campaigns are intended to improve consumer access and stimulate demand. The transition will take time, however, as cultivation, processing capacity and markets develop alongside one another. Over time, the measures could give pulses, oilseeds and other protein crops a larger role in Europe’s food and feed supply.

Aldi Süd takes stake in Philippine discounter Dali

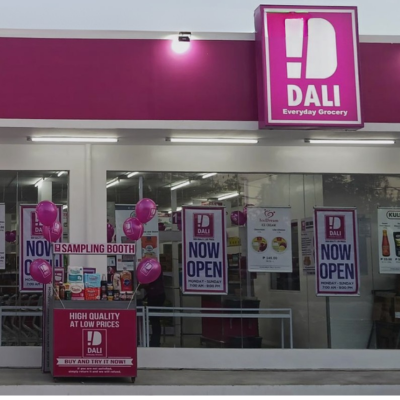
Aldi Süd has acquired a minority stake in DALI Everyday Grocery, a fast-growing hard discounter in the Philippines. DALI operates more than 1,300 stores and will remain independently managed following the transaction.

Besides the name being an anagram of Aldi, founded in 2020, DALI follows a small format, limited assortment model focused on everyday essentials. Its stores typically offer a relatively narrow selection of food and non-food products, with private label products forming an important part of the range. The retailer operates mainly in densely populated residential areas and uses simple store formats and bulk displays to keep operating costs low.

Aldi Süd says the investment will support DALI’s continued expansion across the Philippines, while its local management team retains operational responsibility. The transaction gives Aldi Süd a presence in the Philippine grocery market alongside its existing operations in China and other international markets.

Who do consumers believe?

Consumers are becoming more confident in their ability to make good food choices, but remain sceptical about the information they use to make them. That is the central theme of the latest "Who do consumers believe?" report from the EIT Food Consumer Observatory.

The report looks at food literacy, perceived knowledge and trusted sources of information across 18 European countries. It finds that 72% of consumers consider their knowledge about the healthiness of food sufficient, while 62% say they can determine how healthy a particular food is. Knowledge around sustainability is less developed: 52% feel sufficiently knowledgeable, and 47% say they can judge how sustainable a food is.

At the same time, consumers appear increasingly confident in assessing information for themselves. The proportion who say they can distinguish reliable from unreliable food information rose from 43% to 49% between 2024 and 2025. Yet fewer than half consider food information generally reliable.

The picture is also interesting when looking at who consumers trust. Medical professionals and scientists remain among the most trusted sources, although trust in both is declining. Farmers are the most trusted food-chain actors overall, but trust in manufacturers fell from 41% to 39%. Retailers, meanwhile, are trusted by fewer than a third of consumers as a source of information on the healthiness and sustainability of food.

The report also explores transparency, finding that consumers particularly value accessible ingredient information and the origin of ingredients and processing. It also considers how different forms of transparency, from labels and logos to QR codes and short videos, are received by consumers.

Colruyt incorporates fitness into its retail mix

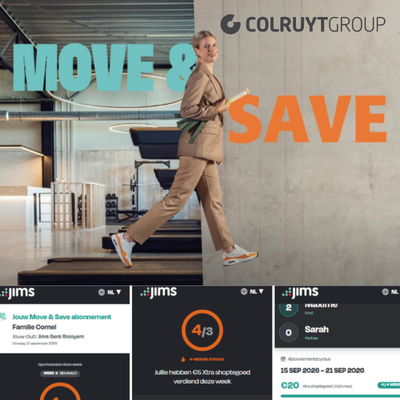
Colruyt Group is finding a new way to connect exercise with grocery shopping, through Move & Save, a family subscription linking its Jims fitness clubs with its supermarket business.

The concept is straightforward: families paying €14.99 a week for a Jims membership can earn €5 in Xtra shopping credit, through Colruyt’s loyalty programme, when they collectively complete at least three workouts in a week. The credit can be used for fruit, vegetables and potatoes, creating a direct link between exercise and fresh food.

The initiative is notable because Jims is not an external partner but part of Colruyt Group itself. The Belgian retailer acquired a majority stake in the fitness chain in 2018 and subsequently took full ownership. That gives the chain the opportunity to connect two businesses that traditionally operate in very different parts of the consumer journey.

For Colruyt, Move & Save is another expression of its ambition to develop from a food retailer into a broader “food & health retailer.” For Jims, it gives the fitness business another role within the group’s wider customer ecosystem.

The PPWR reality check

With the Packaging and Packaging Waste Regulation (PPWR) in application since 12 August, the first weeks of real-world experience are revealing where the mandate is proving difficult to implement. Its objectives remain broadly supported: reducing packaging waste, improving recyclability and creating a more consistent framework across Europe. The frustration is increasingly about how those objectives translate into day-to-day business.

One immediate pressure point is Extended Producer Responsibility (EPR). In simple terms, EPR makes the producer responsible for the packaging it places on the market, including its collection, sorting and recycling, with associated registration, reporting and financial obligations.

This is particularly significant for private label. The Commission's updated FAQs have clarified that a retailer's own brand packaging will generally make the retailer the relevant producer/manufacturer, even where standard packaging is selected and production is outsourced. The practical difficulty is that legal responsibility and access to information do not necessarily sit in the same place. Contract manufacturers and packaging suppliers may hold much of the detailed material and component data needed to demonstrate compliance.

The cross-border administration of EPR adds another layer of complexity. Businesses selling packaged goods in multiple EU countries can face separate national registrations, reporting requirements and, in relevant cases, the appointment of authorised representatives in individual Member States. In practice, this means navigating what can feel like 27 different systems, with different procedures, languages and data requirements. Recent European debate has focused particularly on the burden this creates for smaller and cross-border businesses.

The result is a system that is intended to harmonise Europe's packaging rules and make the Single Market easier to navigate, but which can be difficult and costly for businesses to manage in practice. The Economist, reporting in September on the early impact of the regulation, highlighted smaller retailers that had paused deliveries to some EU countries because of the costs and uncertainty involved.

There is also the question of whether the supporting framework is keeping pace. Some methodologies and detailed rules are still being developed, while businesses are already expected to demonstrate compliance.

So, the first signs are not simply indicating that PPWR creates more work. They point to the fact that responsibility, data and compliance capability are often held by separate businesses within the supply chain. For private label in particular, packaging is becoming a much more significant commercial and supplier-management issue, not simply a technical or sustainability matter.

PLMA's second Private Label Packaging Conference will be held 27 January 2027 in Rotterdam, bringing together private label manufacturers, retailers, and packaging experts to explore the working of the PPWR as well as the latest trends, challenges, and opportunities shaping the future of packaging. For more information click here.


E. Leclerc’s private label continues to grow

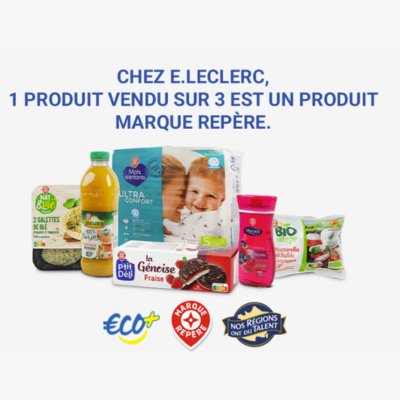
E. Leclerc’s private label business continues to expand, with Scamark, its private label subsidiary, reporting €10.8 billion in revenue in 2025 and 4.9 billion consumer units sold. The business expects sales volume to pass five billion units this year.

Growth has accelerated in 2026. By the end of week 36, volumes were 3.7% higher year on year, while revenue had reached €7.7 billion, up 3%. Scamark currently manages around 7,500 product lines, with more than 350 new products launched in 2025.

Marque Repère remains by far the largest of its private label brands, accounting for 81% of units sold in 2025. Eco+ represented a further 15%, with the remaining volume spread across several smaller brands.

Price remains an important part of the retailer's proposition. Scamark estimates that its products are, on average, around 50% cheaper than national brands, although the difference varies significantly between categories. At the same time, it is putting greater emphasis on developing products rather than simply offering lower-priced versions of existing branded products.

The growth is also placing greater emphasis on sourcing and supply. Scamark works with around 900 suppliers, including 350 French SMEs, and says securing raw materials and production capacity is becoming increasingly important as demand grows.